Table of Content
Use this tool to calculate the maximum monthly mortgage payment you'd qualify for and how much home you could afford. Working towards achieving one or more of these will increase a household's success rate in qualifying for the purchase of a home in accordance with lenders' standards of qualifications. If these prove to be difficult, home-buyers can maybe consider less expensive homes. If not, there are various housing assistance programs at the local level, though these are geared more towards low-income households. Renting is a viable alternative to owning a home, and it may be helpful to rent for the time being in order to set up a better buying situation in the future. For more information about or to do calculations involving rent, please visit the Rent Calculator.
Your interest rate is different from your APR, or annual percentage rate, which includes any loan fees in addition to the interest rate. Get a better idea of how much your closing costs could be when buying a home. Calculate your home mortgage debt and display your payment breakdown of interest paid, principal paid and loan balance over the life of the loan. Using a mortgage calculator is a good start if you’re preparing for buying a home. As you shop home listings, you may also consider a few of these steps. If you’re still shopping, you can put in a ballpark estimate here.
Find Great Mortgage Rates
Just keep in mind that you will need to be a Credit Karma user to use this too, but you can sign up for free now. If your down payment is less than 20 percent of your home's purchase price, you may need to pay for mortgage insurance. You can get private mortgage insurance if you have a conventional loan, not an FHA or USDA loan. Rates for PMI vary but are generally cheaper than FHA rates for borrowers with good credit. When owning a home, you pay annual property taxes based on the assessed value of the property or purchase price of the home, which can affect your affordability. Our calculator assumes a property tax rate by default, but you can edit this amount in the calculator's advanced options.

Take stock of your finances to see if you’re ready to apply for a mortgage. Make sure that you can provide evidence of at least two years’ worth of regular income, and figure out your total assets, debt and monthly expenses. Some communities, such as condominiums and townhomes, are governed by a homeowner's association that maintains communal areas and enforces rules and regulations for a monthly fee. You can edit this number in the affordability calculator advanced options. For example, personal loan terms often range from 12 months to 84 months. Meanwhile, federal student loans typically have much longer terms — potentially stretching from 10 years to 30 years.
Property tax
The home affordability calculator provides you with an appropriate price range based on your input. Most importantly, it takes into account all of your monthly obligations to determine if a home could be comfortably within financial reach. That’s a big deal, because mortgages backed by the Department of Veterans Affairs typically don’t require a down payment.
Lenders take into account the share of your income that goes toward paying debt — or yourdebt-to-income ratio— when determining whether you can afford a mortgage. Add up your debt obligations such as car loans, credit cards, personal loans or other mortgages and enter the total. Keep in mind that home price isn’t the only factor that affects affordability. The interest rate on your home loan, your down payment and your loan term can all affect how much you end up paying for your home.
Rent vs. buy calculator
Traditional mortgages often have 30-year loan terms, but you can also choose to take out a 15-year or 10-year mortgage — or another loan term, if your lender offers one. Shorter loan terms usually mean lower interest rates, but your monthly payment will be higher. Enter the down payment you can afford to make on the home — either a percentage or a dollar amount. For example, you may be able to get a conventional loan with a lower down payment — some lenders allow down payments as low as 3% for qualified buyers. An FHA loan allows you to make a down payment as low as 3.5% if you qualify.
Credit Karma Home can match you with lenders and agents and offers powerful tools and calculators to make the home buying process easier and less stressful. Higher income—Although increasing income is easier said than done, it can culminate in the most drastic change in a borrower's ability to purchase a certain home. A large increase in salary immediately has a large impact on DTI ratios. Acquiring a higher income usually involves different combinations of achieving higher education, improving skills, networking, constant job searching, and typically lots of hard work. Save more—When desired DTI ratios aren't met, mortgage lenders may look at the amount of savings of each borrower as a compensating factor.
Automated Savings Alerts
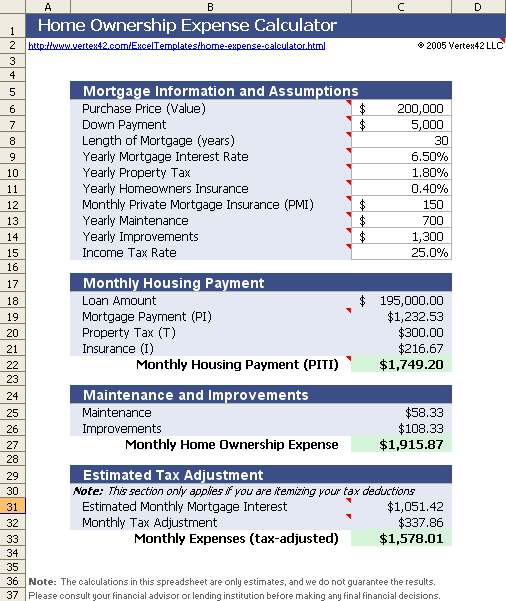
There are two House Affordability Calculators that can be used to estimate an affordable purchase amount for a house based on either household income-to-debt estimates or fixed monthly budgets. For example, if you make $3,000 a month ($36,000 a year), you can afford a mortgage with a monthly payment no higher than $1,080 ($3,000 x 0.36). Your total household expense should not exceed $1,290 a month ($3,000 x 0.43). According to 2020 data from Zillow Research, record low mortgage rates have helped to boost affordability for potential homeowners. The market and share of income spent on a mortgage may fluctuate based on the current mortgage rate, the typical local homeowner's income and the typical local home value. Entering your estimated APR into this field in our loan calculator instead of the interest rate will give you a more accurate idea of your potential monthly payment.
That way, you can then track the value and amount of equity you have on your home at any time with an optional feature enabling you to enter your current mortgage rate. It’s all based on your credit score, ZIP code, and mortgage amount, so there’s no need to answer lengthy or invasive questionnaires to search for the offers that are most suitable for you. Credit Karma can also provide advice on how to improve it and figure out the best methods for you to consolidate any existing debt. USDA loan —You might be eligible for a USDA loan if you’re planning to buy a home in a rural area. There are also state and local programs that offer subsidized loans or help with down payments. Low down payment mortgagesLooking for a low down payment home loan?
Conventional lenders often assess mortgage insurance to cover their losses if you default, and it’s usually part of your monthly payment. When it comes to calculating affordability, your income, debts and down payment are primary factors. How much house you can afford is also dependent on the interest rate you get, because a lower interest rate could significantly lower your monthly mortgage payment.
Some of the most highly-rated credit cards--especially those with excellent rewards--are only available to those with excellent credit. But that doesnt mean you cant get a card with decent rewards even if you have average-to-fair credit. You can use many of the service’s tools, such as the rate search and calculators, without having to set up an account at all. For many people, a home is the most expensive thing they’ll ever purchase. Debt payments are payments you make to pay back the money you borrowed.
Down payments as low as 3%, although qualifying is a bit tougher than with FHA loans. Veterans or spouse of veterans can qualify for 0% down payment mortgages. Credit score is a key factor in determining if you'll be able to get a mortgage and the rate you qualify for. This is the amount that you pay each month that goes toward paying down the principal of the loan and the cost of borrowing . Once you know how much money you make and how much your fixed expenses are — including how much you want to save — you can figure out what your max budget for rent is.
The mortgage rate you’re offered has a big effect on whether you can afford a home. A lower interest rate can make a mortgage much less expensive, while a higher rate could put a house out of your price range. While the 28% rule is a good starting guideline, there are other factors to think about. Lenders are legally obligated to learn about your assets, expenses and credit history before offering you a mortgage.


No comments:
Post a Comment